How does the weather in Arkansas affect home insurance?
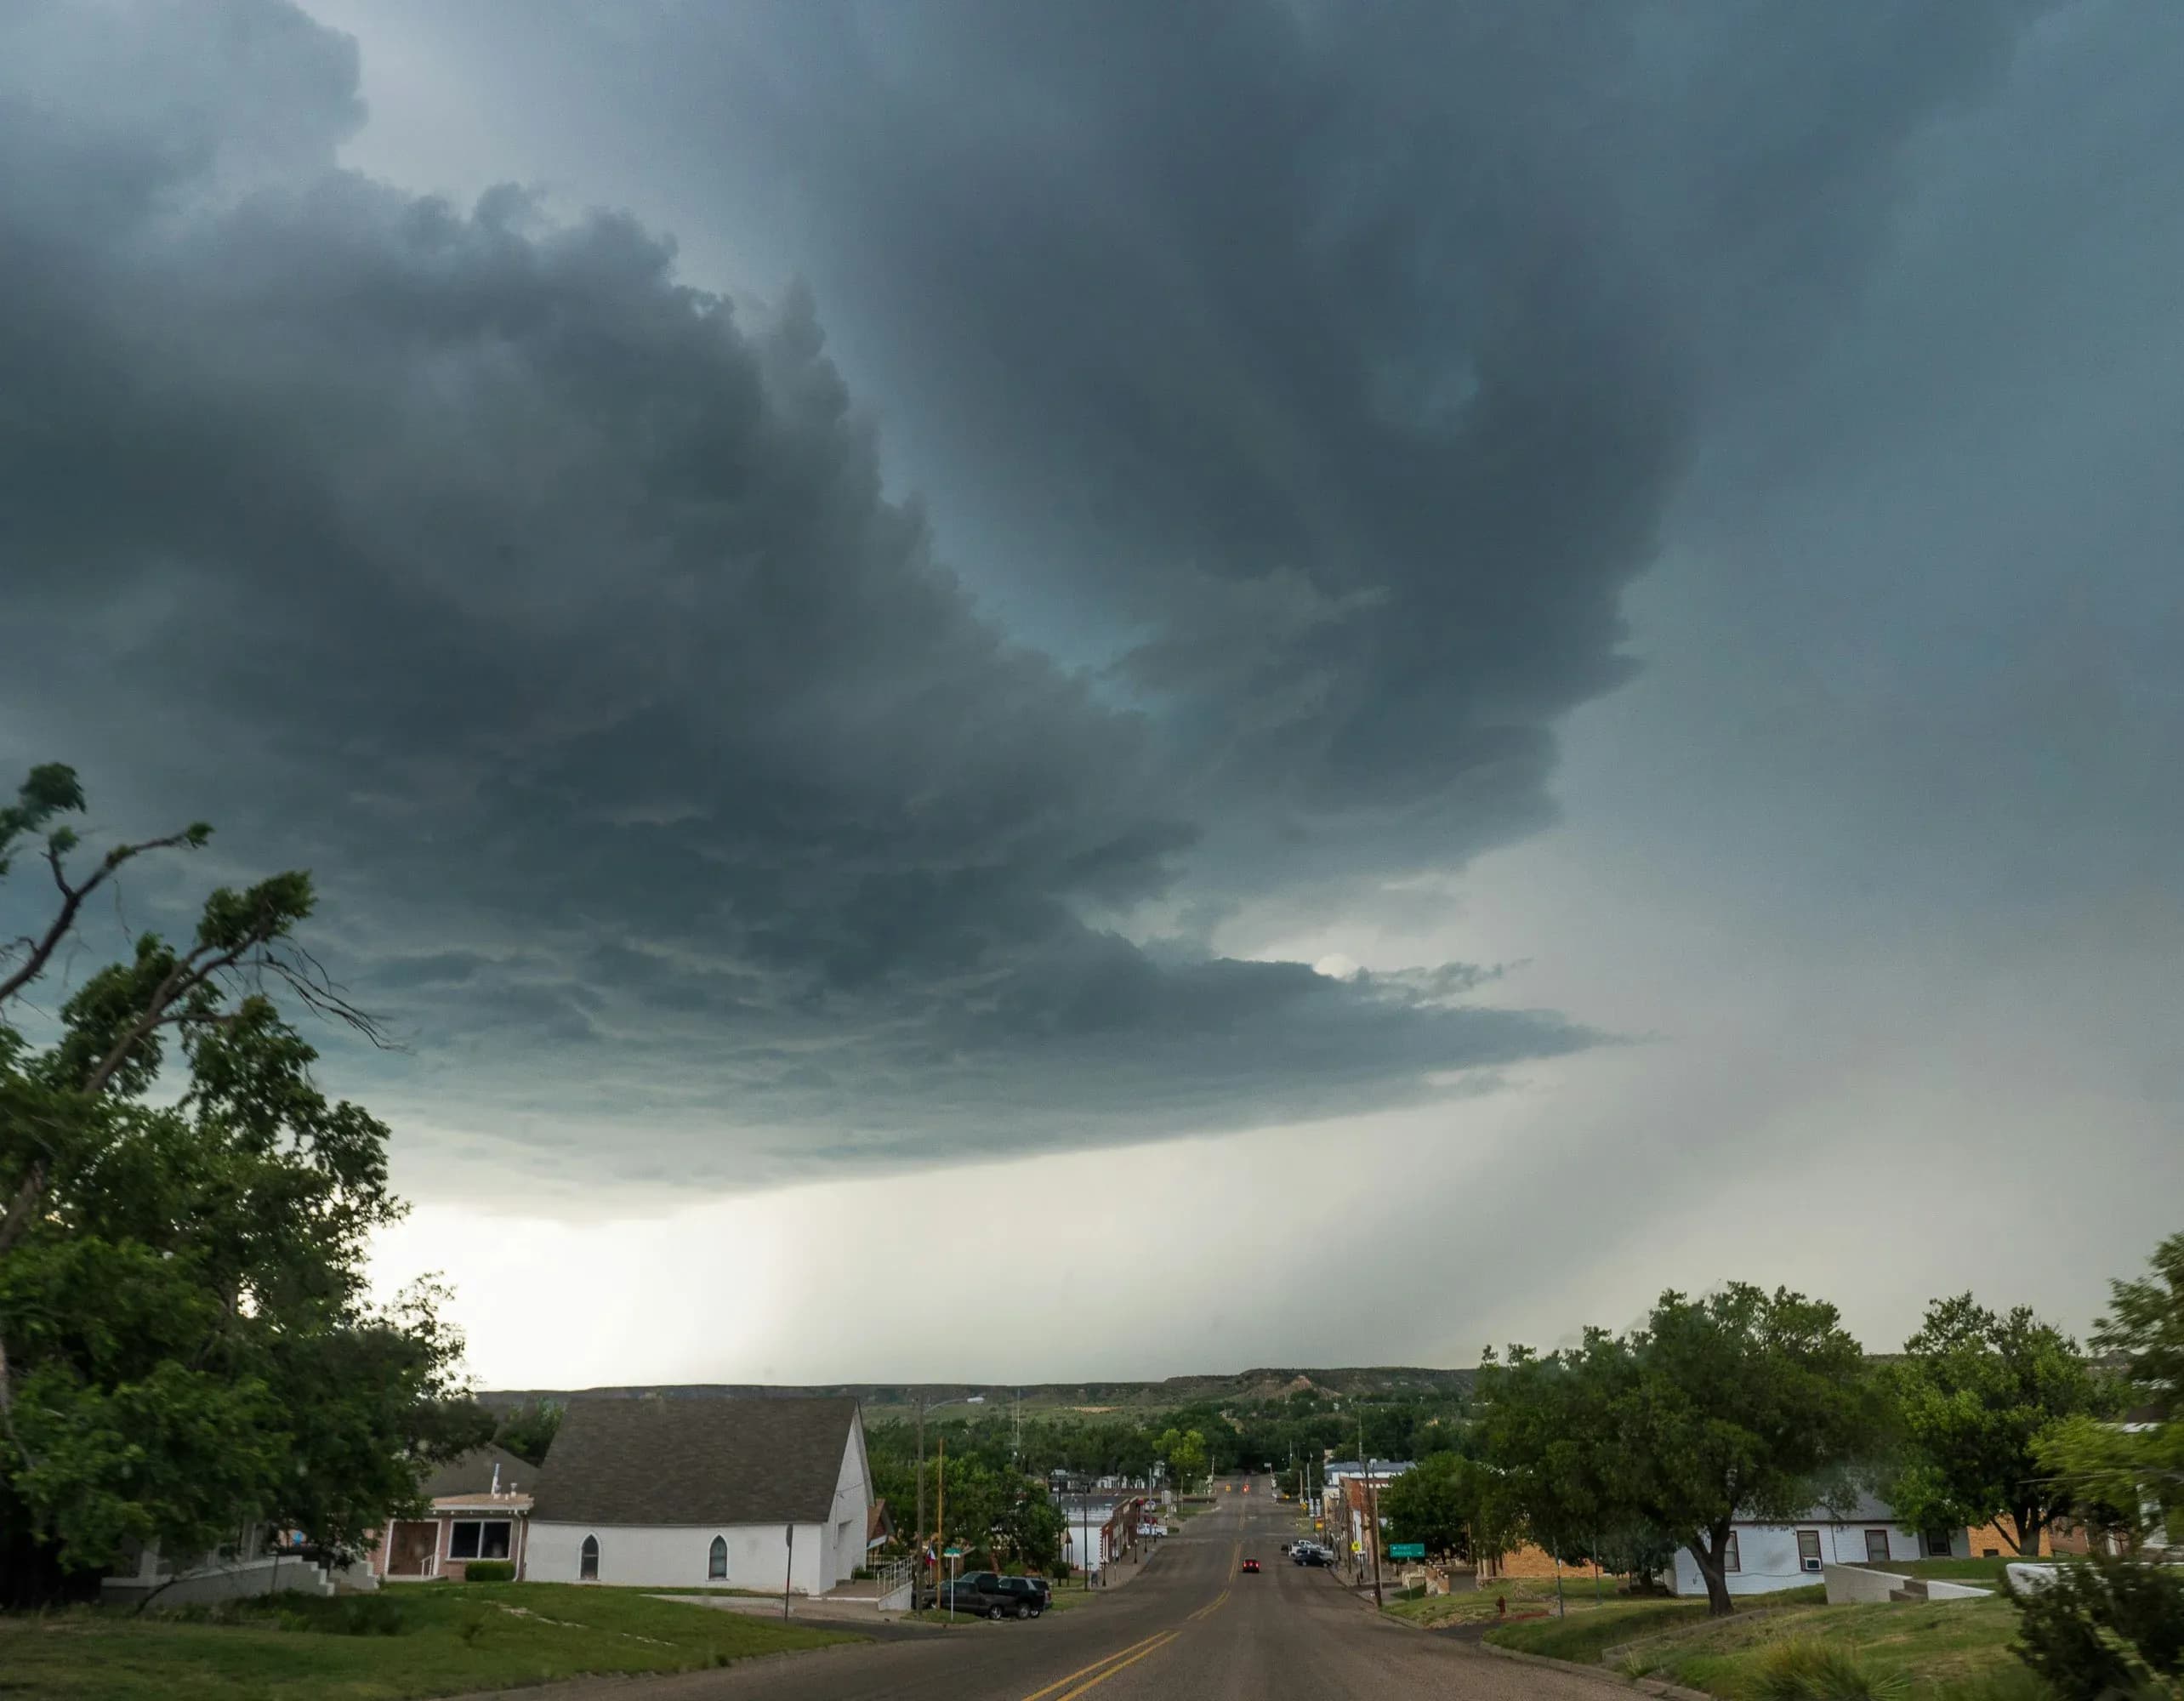
Although Arkansas is best known for frequent tornadoes, the greatest impact on insurance risk calculations in the state actually come from straight-line windstorms that often form in “The Wonder State” in the spring and then rush across the Southeast.
Northwestern Arkansas is part of a region that sees more derecho winds than any other part of the U.S. These high-speed, long-range wind events can result in some of the most widespread property damage seen in the country. Because of the breadth of derecho windstorms and their tendency to travel long distances at great speed, taking down hundreds of trees and utility poles as they go, these storms can be even more costly to a state than a tornado.
Notable winds (including both derecho and non-derecho winds) have occurred on 9% of days in Arkansas since 1950.
Arkansas’ relatively high level of risk of wind and hail damage, as compared to many other states to the north and east, is a primary reason for increasing home insurance costs across the state.
What can Arkansan homeowners do to control insurance costs?
Homeowners do have cost-cutting options to consider when their next home insurance renewal is coming around. Following the passing of Arkansas state bill 366 (SB366) 2025 and its effective date of January 01, 2026, the Strengthen Arkansas Homes Program Fund exists to provide assistance to homeowners in the form of financial grants meant for the improvement of home construction and a reduction in the need for future claims made on home insurance policies.
The use of Class-4 impact-resistant shingles, for example, means that a home is safer in a hailstorm and significantly less likely to take on damage that would require repair and a possible claim on the homeowners policy.
How can a higher deductible help me spend less on insurance?
Accepting a higher wind and hail deductible in conjunction with an add-on deductible relief policy is another option for lower total insurance costs for Arkansas homeowners. With the trade-off of a higher wind/hail deductible on your homeowners policy, a lower premium cost can be negotiated with the home coverage provider.
Part of the savings from the lower annual cost can be used to purchase a Wind and Hail policy from Sola, which can be written to cover the exact dollar amount of the home deductible owed, in the event that a claim needs to be filed. This payout means that your home hail deductible would be covered with zero dollars out of your pocket for filing the claim.
Get a free quote for Sola Wind and Hail today
The combined price of the two policies, standard home insurance and add-on wind and hail deductible gap coverage, will still result in savings in the homeowner’s total overall annual insurance bill.
How else are home insurance laws different in Arkansas?
- Clear and conspicuous disclosure of all deductibles and their costs must be easily findable on the disclosure page for any policy purchased.
- Carriers may now transition homeowner policies from replacement cost coverage to ACV coverage after 7 years, down from the previously required interval of a full 10 years. Homeowners should maintain awareness of their level of coverage and any exclusions or limitations that may be noted on their policy’s declarations page.
- Arkansas was the last state in the U.S. to allow a wind and hail deductible to be split out from the primary home insurance policy deductible. Seen as an effort to control the cost of insurance for homeowners in states with higher risk levels, this change in policy allowed insurers to break out the deductible for windstorm and hailstorm damage and price that piece separately.
The most common practice in Arkansas and most other surrounding states is to price the primary home policy’s deductible as a flat fee (often $1,000 or $2,000) while requiring a percentage deductible for the wind/hail coverage that is calculated as 1%-2% of the property’s total insured value.
While Arkansas was the last state to allow this break-out, it is not mandatory across the nation. There are 19 states (plus the District of Columbia) where a separate wind/hail deductible is commonly used or mandated.
The remaining states are left to set their own primary and wind/hail deductibles. In reality this means that flat-rate home hail insurance deductibles are nearly impossible to find, as most insurance carriers have made a 1%-2% wind and hail deductible the only option for homeowners.
Sources:
“Legislators Explores Options for Holding Down Insurance Costs”, Arkansas Senate, Nov. 13, 2024, https://senate.arkansas.gov/senate-news/posts/2024/11/legislators-explores-options-for-holding-down-insurance-costs/
“The New Math of Storm Damage: Why NW Arkansas Homeowners Are Paying Thousands More Despite Having Insurance”, Patch: Bentonville, AR, Sep. 25, 2026, https://patch.com/arkansas/bentonville-ar/new-math-storm-damage-why-nw-arkansas-homeowners-are-paying-thousands
Gray is the Senior Content Specialist at Sola Insurance, working with the Sales and Marketing teams to provide helpful, valuable content for homeowners and agents. Gray has worked previously in finance, logistics, and advertising.