To make sure you can repair your Kansas home in the case of a severe weather disaster that damages or destroys it, you should maintain active wind and hail home insurance. Read on for more details about how to find the right coverage for your home.
What does Kansas law say about home wind and hail insurance?
As in the rest of the United States, homeowners insurance is not required by Kansas state law. However, home insurance coverage is a requirement of most home loans or home financing agreements. There may also be requirements set by homeowners associations or other authorities. In high wind-risk states like Kansas, wind and hail coverage is often required to be offered, although it may be priced separately than the main policy.
Does wind and hail insurance have a deductible?
Wind and hail coverage that’s included as part of a homeowners insurance policy will always be written with a deductible, and in most states, that wind and hail deductible will be priced separately from the rest of the policy.
Supplemental coverage, a deductible buyback policy, or a deductible assistance insurance policy may be written without a deductible.
Are deductible regulations different in Kansas?
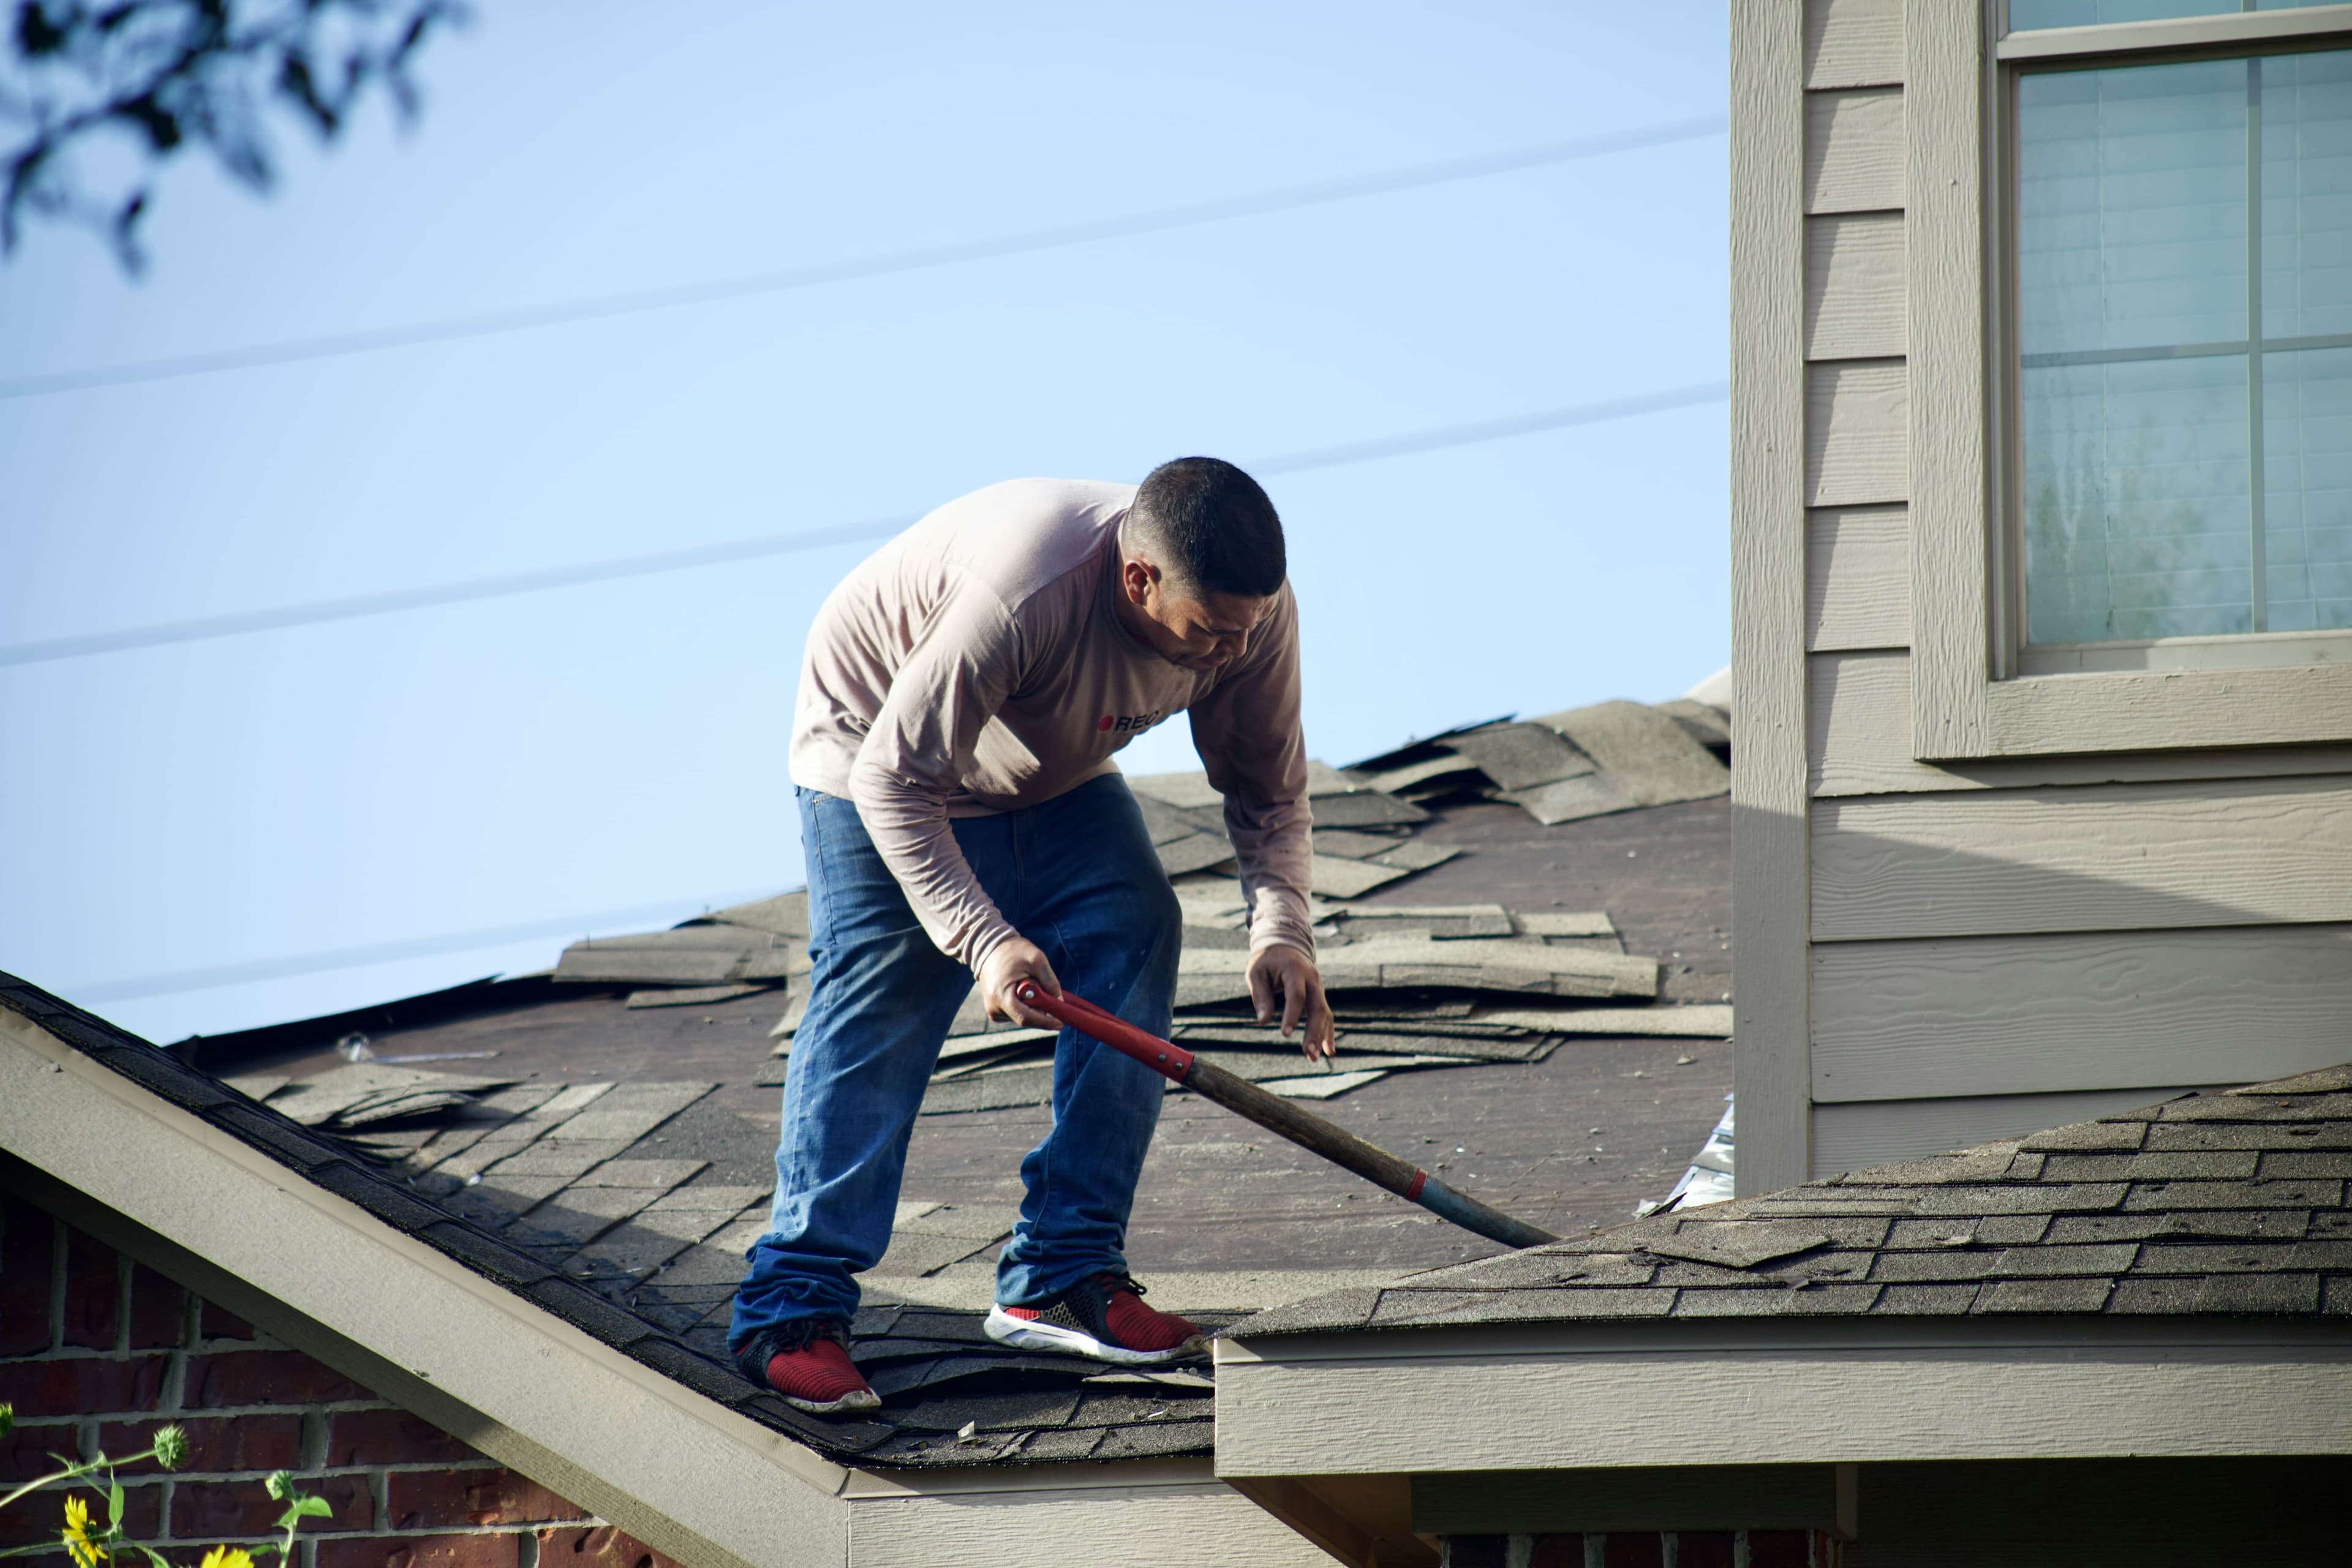
Kansas state law does include a restriction on who can pay the deductible for a roof repair job. The rule specifies that a roofing contractor may not waive, absorb, or offer to pay the deductible in place of the homeowner. This practice is often used as an incentive to get the roofer’s company hired for the job. Although the ‘waived deductible’ offer was commonly used in the past, it should be a sign of trouble for modern homeowners looking to stay in good standing with their insurance providers.
What causes most home insurance claims in Kansas?
Wind and hail damage are the most common reasons for home insurance claims in Kansas. The nearly constant winds across the state combined with other environmental factors bring about thunderstorms, tornadoes, hailstorms, and other wind-driven weather disasters. The roof of your home takes the majority of the damage from these storms, and hail and wind are the leading damaging perils that you have to consider when selecting a home insurance policy.
Although in some years the most costly weather danger in Kansas is drought, that title often trades off with severe convective storms, a category which includes tornadoes, thunderstorms, and hailstorms. Even in years when storms aren’t the most costly peril in Kansas, they are still likely to be the main driver of home insurance claims because of the physical damage that strong winds and hail cause homes every year.
Is wind/hail insurance different from roof insurance?
Wind and hail insurance is sometimes also called roof insurance. These names could refer to the roof coverage that is part of a homeowners insurance policy, or to a standalone hail or roof policy that provides a payout to help cover wind and hail deductibles or other related expenses.
What are my options for discounted roof insurance in Kansas?
- Ask about bundling your different insurance policies. Insurance carriers are often willing to offer their best prices to customers buying multiple policies.
- Install class-4 impact-resistant roofing shingles before your next renewal, and inform your insurer. Using improved roofing materials makes for a stronger, more storm-resistant roof that is less likely to cause a claim in the future.
- Buy a supplementary deductible insurance policy to cover the high deductible for your wind coverage. With this covered, you can carry a higher deductible, which should allow for a lower premium paid for the policy. The savings from this change, even with the added cost of the supplemental insurance, should lower your total insurance bill significantly.
What can Sola Wind/Hail Insurance help with?
Sola’s Wind and Hail coverage provides a fast payout after your home takes damage from wind or hail storm conditions. This money can be used to cover the percentage deductible owed for your home wind and hail coverage or to fill the depreciation gap between your home insurance payout and the amount you actually need to cover a full roof replacement or repair at today’s prices.
Kansas will always have its windstorms, tornadoes, and occasional hailstorms, and your home should always be prepared for these hazards. Contact your local independent agent if you have further questions about additional roof coverage in Kansas, or other aspects of your home insurance policy.
Updated: October 01, 2026
Sources:
“Understanding your insurance deductibles”, Triple-I Blog, https://www.iii.org/article/understanding-your-insurance-deductibles
“Red Flags Specific to Kansas”, SidingQuotesNearMe, Sep. 11, 2026, https://www.sidingquotesnearme.com/siding/kansas
“Residential real estate insurance policy”, Kansas Office of Revisor of Statutes, https://www.ksrevisor.gov/statutes/chapters/ch50/050_006_0143.html
“Billion-Dollar Weather and Climate Disasters”, NOAA National Centers for Environmental Information, https://www.ncei.noaa.gov/access/billions/summary-stats/KS/2024
Gray is the Senior Content Specialist at Sola Insurance, working with the Sales and Marketing teams to provide helpful, valuable content for homeowners and agents. Gray has worked previously in finance, logistics, and advertising.